How to Calculate EMI on a Business Loan (Formula and Examples)
 GrowthLife
29 Oct 2026
4 min read
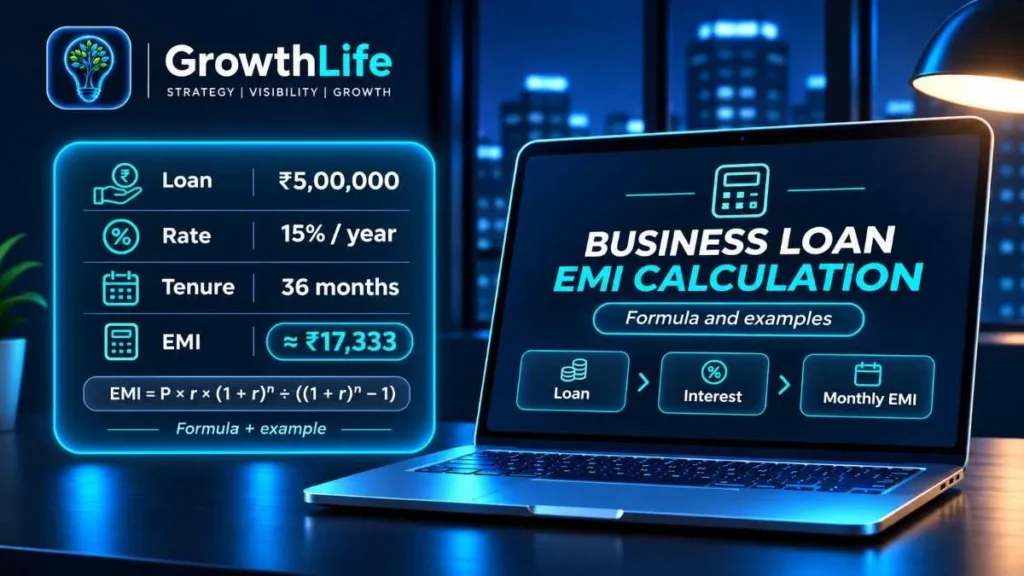
To calculate the EMI on a business loan, use EMI = P × r × (1 + r)n ÷ ((1 + r)n − 1), where P is the loan amount, r is the monthly interest rate (yearly rate ÷ 12 ÷ 100) and n is the number of months. For example, a ₹5 lakh business loan at 15% for 3 years has an EMI of about ₹17,333 and total interest of about ₹1.24 lakh. The fastest way is our free EMI calculator, which also shows a year-by-year schedule.
Quick summary
- Formula: EMI = P × r × (1 + r)n ÷ ((1 + r)n − 1)
- Monthly rate: divide the yearly rate by 12 and by 100. 15% a year is 0.0125 a month.
- Watch out: a “flat rate” quote costs far more than the same number as a reducing rate.
- Lower your EMI: longer tenure, lower rate, bigger own contribution, or part-prepayment.
Step-by-step: EMI on a ₹5 lakh business loan
Loan ₹5,00,000, interest 15% a year, tenure 3 years.
- Monthly rate: r = 15 ÷ 12 ÷ 100 = 0.0125
- Number of months: n = 3 × 12 = 36
- Growth factor: (1 + r)n = 1.012536 ≈ 1.564
- EMI: 5,00,000 × 0.0125 × 1.564 ÷ (1.564 − 1) ≈ ₹17,333
- Total repaid: 17,333 × 36 ≈ ₹6.24 lakh, so total interest ≈ ₹1.24 lakh
In the first month, ₹6,250 of the EMI is interest (₹5,00,000 × 0.0125) and about ₹11,083 reduces the loan. Each month the interest share falls and the principal share rises, because interest is charged only on what is still outstanding.
Business loan EMI examples
| Loan | Rate (per year) | Tenure | Monthly EMI | Total interest |
|---|---|---|---|---|
| ₹2,00,000 | 12% | 2 years | ₹9,415 | ₹25,953 |
| ₹5,00,000 | 14% | 3 years | ₹17,089 | ₹1,15,197 |
| ₹5,00,000 | 16% | 3 years | ₹17,579 | ₹1,32,827 |
| ₹10,00,000 | 16% | 2 years | ₹48,963 | ₹1,75,115 |
| ₹10,00,000 | 16% | 3 years | ₹35,157 | ₹2,65,653 |
| ₹10,00,000 | 16% | 5 years | ₹24,318 | ₹4,59,083 |
These rates are examples to show how the maths works. Your lender’s rate depends on your credit score, turnover, business age and whether the loan is secured.
Look at the last three rows: stretching ₹10 lakh from 2 to 5 years halves the EMI but adds about ₹2.8 lakh of interest.
Flat rate vs reducing rate: the trap to avoid
Some lenders quote a flat rate, where interest is charged on the full loan for the whole tenure even as you repay. Banks usually quote a reducing rate, charged only on the outstanding balance.
| ₹5 lakh for 3 years | Monthly EMI | Total interest |
|---|---|---|
| 10% flat rate | ₹18,056 | ₹1,50,000 |
| 15% reducing rate | ₹17,333 | ₹1,23,976 |
A 10% flat rate is roughly the same as an 18% reducing rate. Always ask the lender for the reducing rate (or the annual percentage rate) before you compare offers.
What else adds to the cost
- Processing fee: often a percentage of the loan, deducted upfront, plus 18% GST on the fee.
- Prepayment or foreclosure charges: check them before you sign if you plan to repay early.
- Insurance and documentation charges: sometimes added to the loan amount.
- Late payment penalties: a missed EMI also hurts your credit score.
How to lower your business loan EMI
- Choose a longer tenure for a lower EMI, if cash flow is tight. You will pay more interest overall.
- Put in more of your own money so you borrow less.
- Compare at least three lenders on the reducing rate and total cost, not just the EMI.
- Prepay when you have spare cash. On ₹10 lakh at 16% for 5 years, paying ₹1 lakh extra after the first year and keeping the same EMI ends the loan about 7 months early.
- Check government schemes. PM Mudra loans cover non-farm micro businesses up to ₹20 lakh, with Shishu loans up to ₹50,000 and Kishor up to ₹5 lakh, usually without collateral.
Can your business afford the EMI?
A simple rule: total EMIs should stay under about a third of your monthly profit before loan payments, so a slow month doesn’t put you in default. Before you borrow, check the return the loan will bring with the ROI calculator, and test your pricing with the profit margin calculator.
Starting small? See our list of business ideas under ₹1 lakh, many of which need no loan at all.
Frequently asked questions
How is EMI calculated on a business loan?
With the reducing-balance formula EMI = P × r × (1 + r)^n ÷ ((1 + r)^n − 1), where P is the loan amount, r the monthly interest rate and n the number of monthly instalments.
What is the EMI on a ₹10 lakh business loan?
At 16% a year, it is about ₹48,963 for 2 years, ₹35,157 for 3 years and ₹24,318 for 5 years.
What is the difference between flat and reducing interest rates?
A flat rate charges interest on the full loan for the whole tenure. A reducing rate charges only on the outstanding balance. A 10% flat rate costs about the same as an 18% reducing rate.
Does prepaying a business loan reduce EMI?
It can reduce either the EMI or the tenure, depending on what you ask the lender for. Keeping the EMI and cutting the tenure saves the most interest.
Is GST charged on business loan EMI?
No. Interest on loans is exempt from GST. GST applies only to fees such as the processing fee.